A strong scheme still needs the right case put in front of the right lender.
We package your experience, your numbers and your plan properly, match you to a lender whose appetite genuinely fits your scheme, and stay involved through the build and the exit — not just the drawdown.
Two things decide whether a lender says yes
A good scheme isn’t enough on its own — how your experience is presented, and whether the lender’s appetite genuinely fits your project, matter just as much as the numbers.
Putting your experience forward properly
Lenders back developers, not just developments. We build a case that shows your experience clearly — including where a scheme sits just outside your comfort zone, and how we’ve mitigated that.
- A structured track record schedule, not a scattered CV of past projects
- Honest positioning where experience is limited, backed by the right team around you
- Evidence of past schemes delivered on time and on budget, presented the way underwriters actually read it
- First-time developer schemes structured with extra support built in, not talked up unrealistically
Matching the scheme to the lender, not the other way round
Every development lender has a different appetite — GDV range, build type, location, experience threshold. We know which lenders actually want your kind of scheme before we ever submit.
- Ground-up, conversion, and heavy refurbishment schemes each suit different lenders
- Regional appetite varies — a lender keen on one region isn’t always keen elsewhere
- Rate isn’t everything — we weigh appetite, flexibility, and drawdown speed together
- No speculative submissions — every application goes to a lender already inclined to say yes
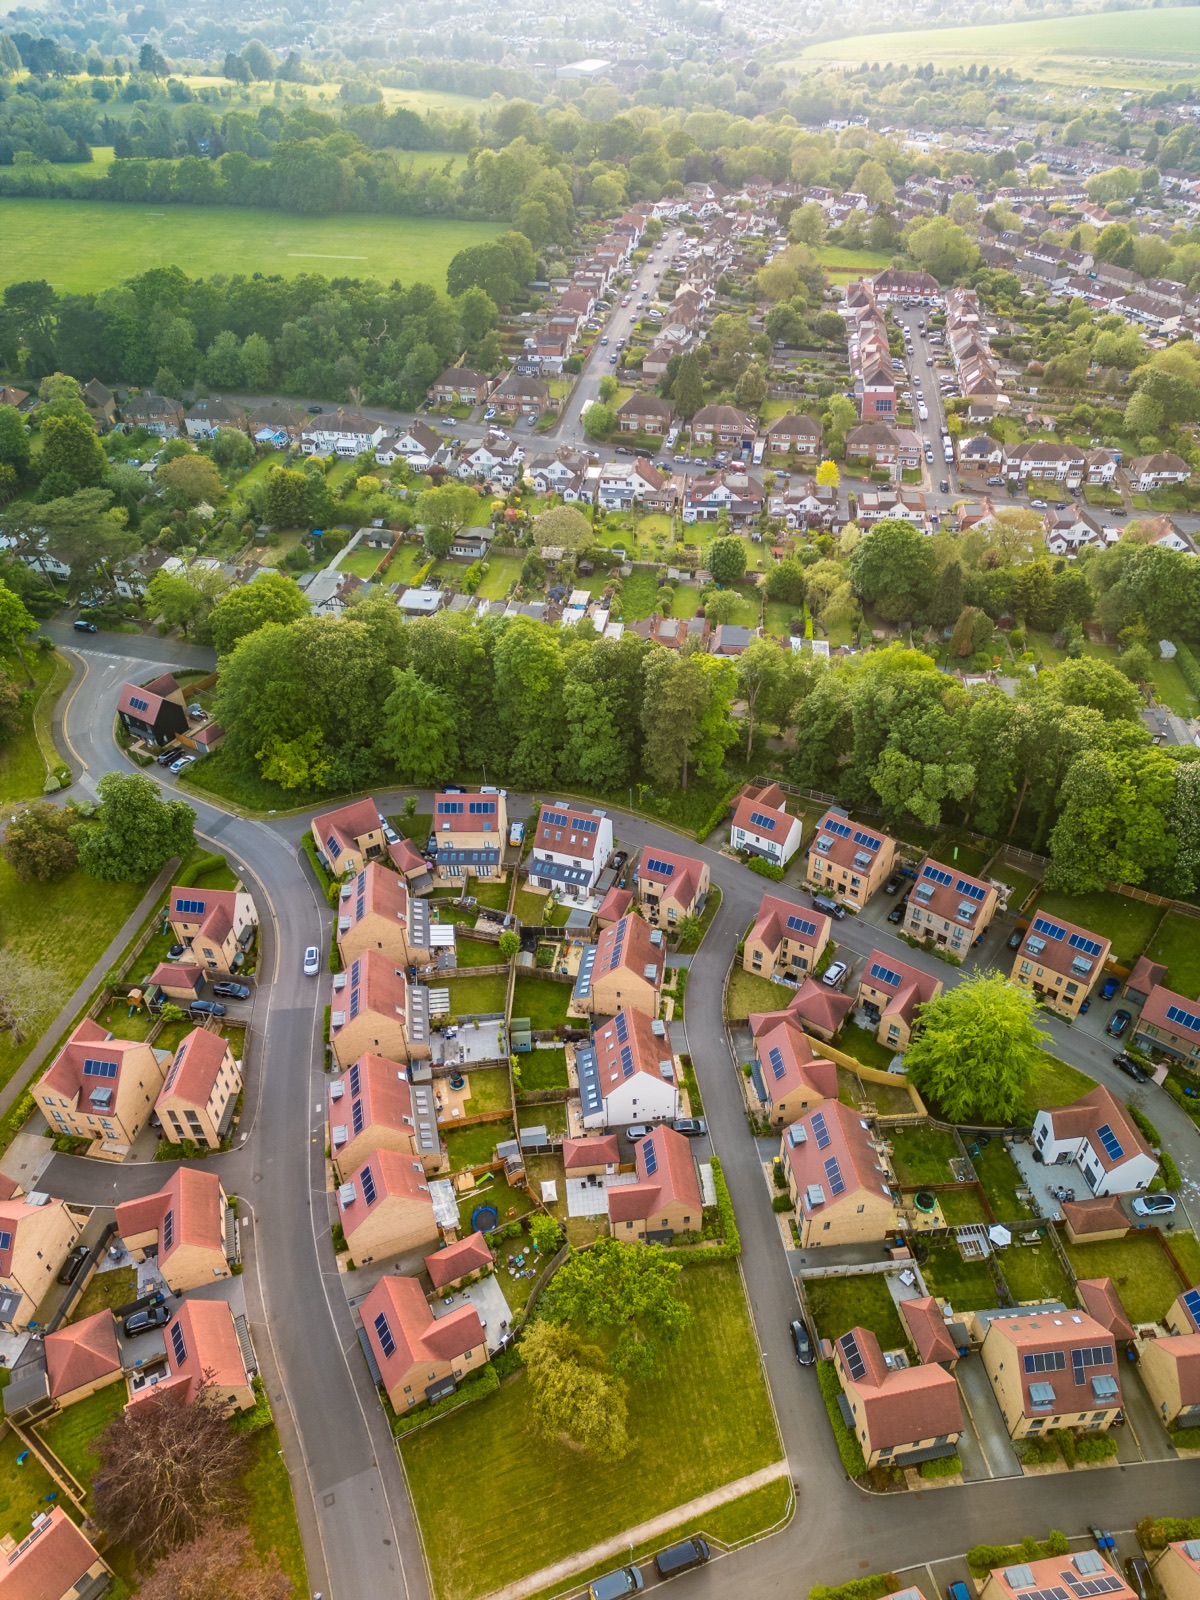
£3.78m Development Facility for an 18-Unit Semi-Detached Scheme
The Challenge
Our client, an experienced residential developer, secured a site with planning consent for a scheme of 18 semi-detached houses, with a projected Gross Development Value of £5.4m on completion. The client needed a development facility to fund site acquisition and the build programme through to practical completion and sale, without over-leveraging the scheme or accepting onerous drawdown terms that would slow the build.
With a scheme of this scale, the client needed a lender comfortable underwriting both the build cost profile and the sales strategy for 18 units, alongside a monitoring surveyor process that wouldn’t create bottlenecks at each drawdown stage.
The Approach
Using our accountant’s-eye view of the appraisal, we stress-tested the scheme’s build costs, contingency, and projected sales values against the £5.4m GDV before approaching lenders, giving us a clear picture of what facility size and structure the numbers could comfortably support.
We then placed the facility with a development lender able to fund at 70% of GDV, structured with staged drawdowns against the build programme and a monitoring surveyor process built around the scheme’s timeline rather than a generic template — keeping funds flowing at the pace the build required.
The Insider’s Edge
Stress-testing the appraisal before approaching lenders, then matching the scheme to a lender whose drawdown process fits the build — that’s the Accountant’s Eye, the Investor’s Instinct, and the Consultant’s Reach working together on a development deal.
From site purchase to a term mortgage exit, without a single stalled drawdown
The Story
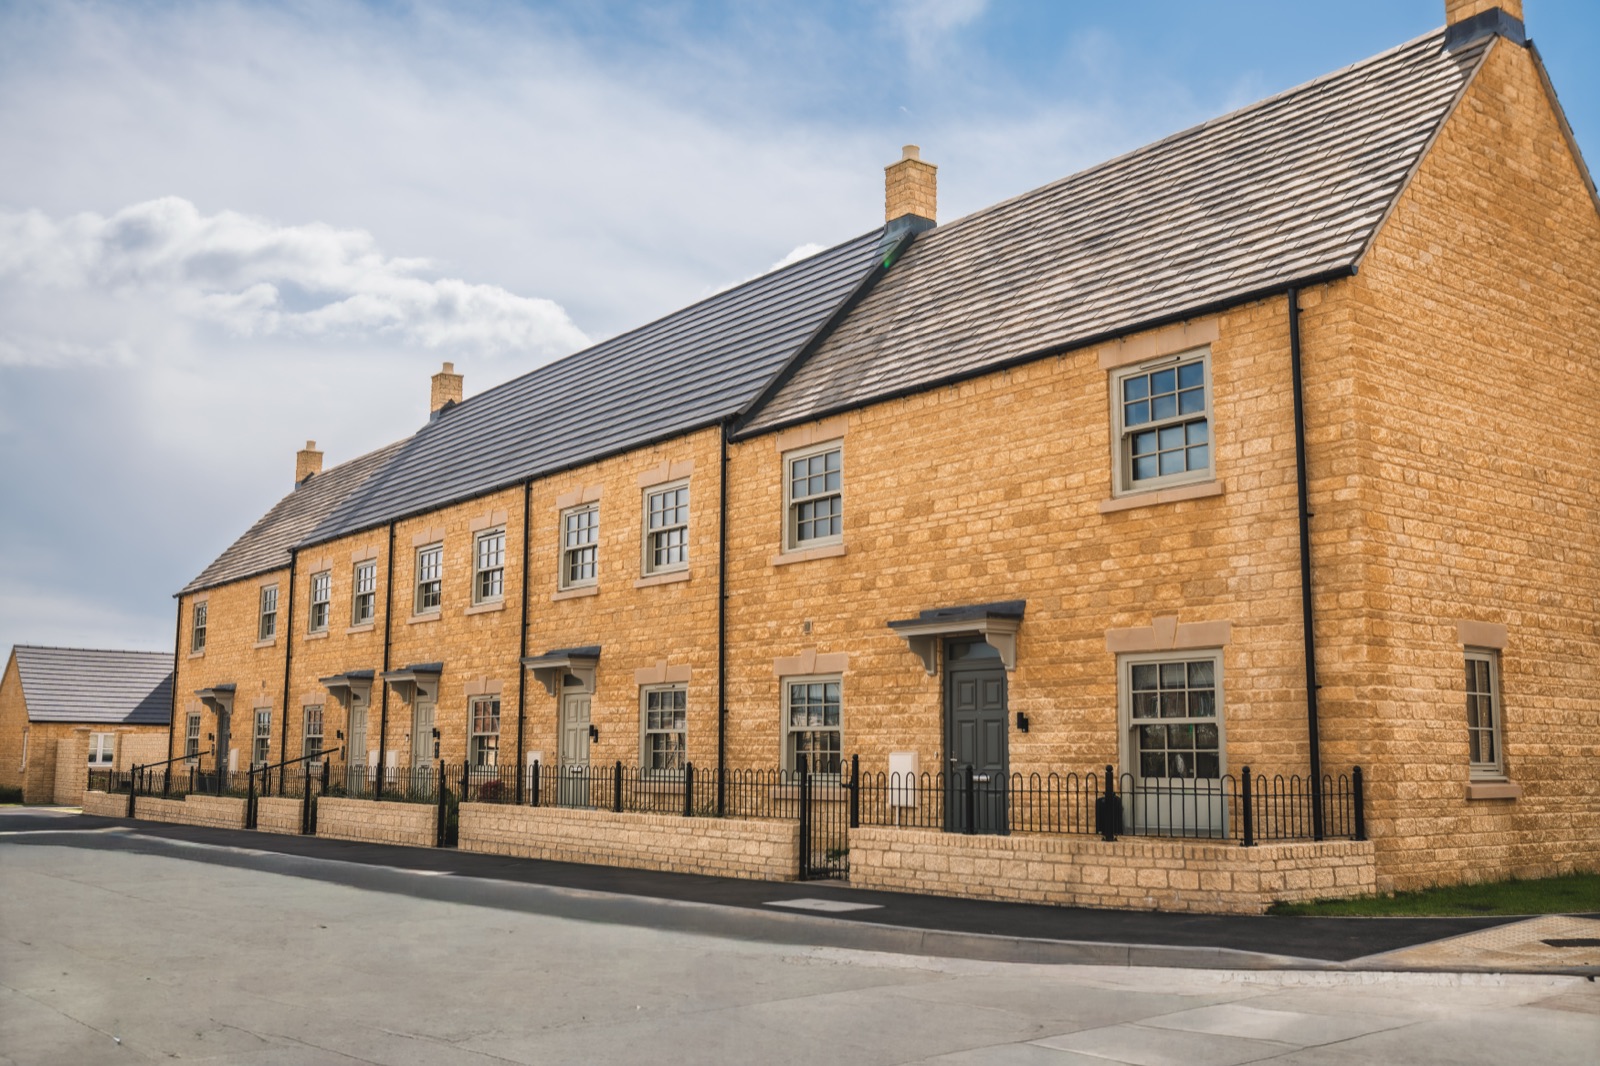
Our client had completed one small conversion scheme and wanted to move into ground-up development — a step change most lenders view cautiously. Rather than approaching lenders broadly, we built a track record case that presented the first scheme’s numbers clearly, and paired it with a specification and contractor team strong enough to support the step up.
We approached a lender whose appetite specifically favoured first-time ground-up developers with a completed conversion behind them, rather than a generalist lender who might have viewed the experience gap as a reason to decline. Terms were agreed against a build programme we’d already stress-tested for realistic delays.
Through the build, we stayed in contact with the monitoring surveyor ahead of each valuation visit, so every drawdown request was supported and released without a query holding up the site. The exit — a refinance onto a term buy-to-let mortgage across all six units — was agreed in principle with a lender before the development facility was even drawn, so there was no scramble to find an exit once practical completion was reached.
— Client, Birmingham property developer
Let’s talk about your scheme
Bring us the site, the numbers, and the plan — we’ll tell you honestly what it’ll take to get funded.
Start Your Enquiry